Friday, December 17, 2021

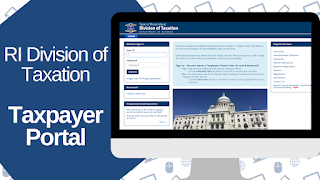
Rhode Island Division of Taxation New Taxpayer Portal


Division's New Taxpayer Portal

Effective January 4, 2022, tax payments can no longer be made using the website which uses the following web address: https://www.ri.gov/taxation/business/index.php. Instead, online debit payments may only be made via the Division’s Taxpayer Portal, which can be accessed via the following address: https://taxportal.ri.gov. 

Learn more: https://tax.ri.gov/media/17931/download?language=en

For questions or assistance, please call the Division at (401) 574-8484. Please activate your Taxpayer Portal account as soon as possible. 

Thursday, December 16, 2021

PPP Loan Forgiveness Basis Issue


Mary Mellem, EA

A cash basis taxpayer reports income as received and expenses as paid.  An accrual basis taxpayer reports income as earned and expenses as incurred.  Naturally this means the forgiveness of a PPP loan is forgiveness income (nontaxable per law) at the time it is forgiven based on the taxpayer’s method of accounting.


IRS Notice 2020-32, released in late April 2020 (a year and a half ago) said the expenses related to PPP loan proceeds were NOT deductible when paid/incurred because they “would result in the forgiveness” and owners’ bases in entities was NOT increased by the nontaxable PPP debt forgiveness.  Both of these were changed on December 27, 2020, when the Consolidated Appropriations Act, 2021 was signed by President Trump.  These expenses became retroactively deductible and partners and S corporation shareholders were retroactively allowed to increase their basis by the forgiven PPP loan.


Because of the original denial of expenses, many taxpayers paid/incurred additional expenses to help keep their income down.  As a result of the retroactive deductibility of the expenses paid with the PPP loan proceeds, many of these taxpayers had losses for the year.  In the case of partnership and S corporations, in many cases the losses exceeded the owner’s basis.


There have been questions on whether the forgiveness could be considered to have happen earlier, such as when the PPP qualifying expenses are paid/incurred.


Now IRS has released Revenue Procedures 2021-48, 2021-49, and 2021-50 dealing with this timing issue.  The question is:  When can a taxpayer treat the PPP loan as forgiven –

1) When the expenses are paid/incurred?

2) When the application for PPP loan forgiveness is filed?

3) When the PPP loan forgiveness actually takes place?


In Revenue Procedure 2021-48, IRS answers this question by saying, effectively, “YES”.  Actually, IRS said the taxpayer can choose any of the above as long as it is consistent with the tax-exempt income resulting from the forgiveness of a PPP Loan being treated as gross receipts under a particular Federal tax provision, including but not limited to IRC §§448(c) and 6033.  IN OTHER WORDS – CHOOSE WHICH OF THE THREE DATES THAT YOU WANT TO USE as long as it is shown as income on the books as of the same date.


The Revenue Procedure also states a partnership or S corporation (plus subsidiary members of consolidated groups) must make the decision of the timing of the PPP Loan forgiveness at the entity level.  If the decision is to treat the forgiveness as if it happened in a prior year, the entity will file an amended return for the prior year.  It appears this amended return can be filed at any time during the normal 3-year statute of limitations as long as the conditions above are met.  (See below if the entity is a partnership subject to the BBA provisions.)


Revenue Procedure 2021-49 addresses the allocation of the PPP Loan forgiveness among the owners of a partnership or S corporation.  Basically, the amount of forgiveness income to allocate to a partner or S corporation shareholder is tied to the PPP Loan related expenses that were allowed to that person.


Revenue Procedure 2021-50 addresses partnerships subject to the Bipartisan Budget Act of 2015 (BBA).  Under §6227, a BBA partnership (a partnership subject to the consolidated audit procedures) is limited in its ability to file an amended tax return.  BBA partnerships must generally file an Administrative Adjustment Request (AAR) under §6227 to make partnership adjustments AND is not allowed to amend its tax return after the due date of the return, UNLESS specifically provided by the Secretary of the Treasury or his/her delegate.


This Revenue Procedure exercises that authority to allow a BBA partnership to file an amended return and furnish Schedules K-1 for taxable years ending after March 27, 2020.  The BBA partnership should file Form 1065 with the “Amended Return” box checked, “FILED PURSUANT TO REV PROC 2021-50” at the top of the amended return, and issuing amended Schedules K-1 to each owner, with this same “FILED PURSUANT…”.  A partner that receives an amended Schedule K-1 must amend the partner’s return.  A BBA PARTNERSHIP’S AMENDED RETURN MUST BE FILED NO LATER THAN DECEMBER 31, 2021.  Otherwise, a BBA partnership is required to go through the AAR procedures, which can be used through the normal 3-year statute of limitations for the applicable tax year.


This text has been shared courtesy of:  David & Mary Mellem, EAs & Ashwaubenon Tax Professionals, 920-496-1065, fax 920-496-9111, ataxprof.com.


©2021 Ashwaubenon Tax Professionals.  No reproduction of this article is permitted without the express written consent of Ashwaubenon Tax Professionals, 2140 Holmgren Way, Suite 1040, Green Bay, WI  54304.

Wednesday, December 15, 2021

What's New at the Mass DOR


What’s new on the “What’s Trending” page

One thing we’re continuing to do is to keep our What’s Trending page updated with all the latest trending topics. We recently added to the page some new timely topics of discussion like, advance payment requirements, E-file requirements, elective pass-through entity excise and more.
 
December deadlines approaching
A few very important deadlines are approaching this month that you should know about. First up is the Health Insurance Responsibility Disclosure (HIRD) filing that is due tomorrow December 15. Two exemption renewals are due on December 31, the Small Business Energy Exemption and the Paid Family Medical Leave exemption. Go to MassTaxConnect to meet all the upcoming deadlines. 
 
Updates on advance payments
New updates in the Advance Payment arena. We’ve added more FAQs and a penalty self-assessment worksheet to the page. Beginning in January 2022, taxpayers will see new lines on returns for advance payment and determine if there is an advance payment penalty using the worksheet. Check out the page to learn more.
 
Estimated payments can be made for PTE
Back in September, Mass legislators moved to create an elective pass-through entity (PTE) excise in response to the $10,000 federal state and local tax (SALT) cap. Entities can now register and make  estimated payments on MassTaxConnect. We’ll continually update the FAQ page. Bookmark the page for easy access.
 
New! Filing season overview webinar
Stay tuned in January for some filing season info. We will be posting a filing season overview video on our website for your viewing. To get ready for 2022, we’ll talk about the Mass/Federal differences, Personal Income Tax updates, Trustee updates, how to report unemployment on a tax return, DOR initiatives and E-file requirements to name a few. We will include a link to the recording in the next edition of DOR News.
 
Also coming soon: PTE excise presentation
Another video will be released soon on the elective pass-through entity excise. We’ll cover all the need-to-know information about the new excise and what to expect. Be on the lookout for that email as well. Most everything you need to know to date is covered on the FAQ page, which is updated as needed.
 
DOR blog – Extra! Extra! Read all about it
Did you know we have a blog? If you didn’t, check it out. Our blog is a space where we go into detail about many topics across the agency. Check out some of the new blogs covering job opportunities at DOR, video resources, and a lot more. Curl up with your laptop and get caught up.
 
MTC video translations now offered in Spanish
Spanish translations are now available for a number of DOR YouTube tutorial videos. We started first with our notices and will continue to identify more ways to assist non-English-speaking taxpayers. To view the translated videos, head over to our YouTube channel.

Thursday, December 9, 2021

Massachusetts / Rhode Island NATP Chapter Annual State Update Seminar

 Massachusetts / Rhode Island NATP Chapter Annual State Update Seminar - January 6th 2022


Join the Massachusetts / Rhode Island NATP Chapter on Thursday, January 6th, 2022 for our Annual State Update Seminar. This all day event will be held at the Southbridge Hotel & Conference Center, Southbridge MA. Registration details are below, and are handled online directly by National NATP. A link to the registration website is listed below. Please take a look at the details on our speakers and topics provided in this great update opportunity including continental breakfast, snacks, lunch, vendors and great networking opportunities PLUS even 2 CE Credit Hours. Registration is from 7:00am to 8:00am & Education is from 8:00am to 5:00pm.
  • Register online with credit card.
  • For more information or to register by phone, fax or mail, use this form.
  • After January 3rd, please register at the door with the form above.
Topics:

Massachusetts State Tax Update presented by Massachusetts Department of Revenue.


Rhode Island State Tax Update presented by Rhode Island Division of Taxation.


Connecticut State Tax update presented by a representative.


New York State Tax Update presented by Kathryn Keane of New York NATP Chapter.


Federal Tax Update presented by Kathryn Keane of New York NATP Chapter. (2 Hours of CE Credits)

Featured Speaker - Kathryn M. Keane, EA.

Kathryn is a principal of Macanta, a small tax and related services practice located in Brooklyn, NY, serving over 850 individual clients and 50 businesses. In December 2006, Kathryn completed two three-year terms on the National Board of Directors of NATP and was twice awarded Chapter Person of the Year for 2002 and 2008 for her volunteer service to the community at large as well as to NATP. In addition to serving as an Education Committee member for NY NATP, she currently serves as Chair of the IRS Tri-Boro Practitioner Liaison Committee. Kathryn is a frequent speaker for NATP Chapters. She has also presented for VASEA, NCCPAC (Nassau-Suffolk County Chapter) and local chapters of NYSSCPA. Kathryn has a B.S. degree from Brooklyn College.

President's Message


Ronald Fisher, EA, President
Massachusetts/Rhode Island NATP Chapter

I am privileged and honored to return once again and serve as President of the Massachusetts/Rhode Island NATP Chapter for 2022. I appreciate the confidence the Board of Directors and the Membership has shown in my ability to lead this organization.

I want to first thank all of you for your membership and support of this chapter.  I also want to remind each of you that my only job is to help you and your business achieve success in the tax profession.  The board and I exist solely to provide support, education and local networking opportunities for our members and we encourage all of you to get connected with the other like-minded professionals in this chapter.

Somehow, we all survived the 2020 tax filing season (and we thought the 2019 tax filing season was the worst)!  Changing tax laws for unemployment and the PTC in March of 2021 that affected 2020 tax returns, State delays deciding what they would do with those changes, explaining preparation  delays to countless clients daily, delayed IRS processing of tax returns and refunds that included unemployment, stimulus and PTC requiring manual IRS review, IRS delays in responding to communications, inability to reach anyone at the IRS, extending the due date to May, continuing issues with covid 19, etc., etc., all contributed to a colossal new level of challenges for all of us.  Shortly, the 2021 tax filing season will begin.  Let’s hope it goes easier on all of us.

From a chapter perspective, we returned to “in person” teaching in 2021 and I urge all of you to register and participate in Chapter education events.  It is the best way for you to meet, connect and build solid professional relationships with other local tax preparers, get assistance and learn how they handle difficult tax situations.  You can learn about all upcoming chapter events on our website - www.massrinatp.com.  As a reminder, our next event, the State tax update, is scheduled for January 6, 2022 at the Southbridge Hotel and Conference Center.

Lastly, if you are interested in becoming more involved and serving on the board, working along with our very experienced and dedicated board members, please send me an email (rfishertax@aol.com).  I would be happy to talk to you and let you know what is involved in being a member of the Massachusetts/Rhode Island board.  

If there is ever anything that you need, please reach out to me or any of the other board members.  My number is (508) 735-6607.  I wish you all a healthy and prosperous 2022!

Ron Fisher, EA

President